
The global forest sector is worth approximately USD1.5 trillion, equivalent to the economies of Indonesia or the Netherlands. That value includes timber, climate regulation, water supply, non-timber forest products and the informal economies of hundreds of millions of rural households.
Yet financing for forests remains inadequate, highly fragmented and chronically dependent on public funds and donor grants. Current funding is nowhere near what is needed.
In 2023, the world lost 3.7 million hectares of primary tropical forest, the highest rate in recent years, representing an enormous threat to biodiversity. Approximately 1 million species are threatened with extinction, a figure that has not decreased despite a decade of international negotiations.
Public financing for forest restoration averages roughly USD5.7 billion per year, a tiny fraction of the estimated USD 117 billion to USD 300 billion needed annually.
What would it take to increase forest finance, make it more efficient, and attract more private-sector investment in restoration and sustainable forest management?
A new report on forest finance landscapes, commissioned by the European Union’s Forests for the Future Facility (F4F) and produced with the Center for International Forestry Research and World Agroforestry (CIFOR-ICRAF), offers insights drawn from 11 country-level appraisals covering Colombia, Suriname, Guyana, Lao PDR, Papua New Guinea, Morocco, Cameroon, Gabon, the Republic of Congo, the Democratic Republic of Congo and Zambia.
The report maps the instruments being used, identifies what is working and diagnoses why most of these efforts have never scaled up. The findings are not optimistic, but they point to pathways for improvement.
“Many finance tools already exist,” said study co-author Ludwig Liagre. “Often, what is needed is closer analysis to determine the shape the financing should take. There is no single solution — it will always be a mix of public and private finance. The challenge is to ensure that the conditions for private investment exist. Because most forests are on public lands, however, governance issues must be addressed before private investment can increase.”
Researchers assess an Afrormosia tree in Yangambi, Democratic Republic of the Congo. Photo by Axel Fassio / CIFOR-ICRAF
Forests’ economic value remains untapped
The report’s first structural observation is one often obscured in the forest finance discussion: the forest sector, despite its ecological and social significance, is not a dominant contributor to the gross domestic product (GDP) in most countries. Globally, agriculture outweighs forestry by a factor of approximately six.
In countries with temperate forests, the sector is important for employment and exports, particularly through value-added products that generate higher revenues from processing, engineering and branding. Those countries, over decades, have successfully shifted from selling timber volume to selling wood value.
That transition has largely not happened in tropical-forest countries. Timber exports contribute to national GDP, but processing capacity remains limited, infrastructure is often outdated, and value chains are informal and fragmented. In much of the tropical world, forests matter above all as a source of rural employment, an income buffer in difficult seasons and an energy source. Although these are significant contributions to local communities, they do not attract private investment.
The bottleneck in forest finance is not a shortage of forest resources. The 11 countries assessed contain some of the most biologically and economically significant forests remaining on Earth. The bottleneck is a combination of finance, governance and risk.
In many countries, land tenure insecurity makes investment legally precarious. Concession frameworks are outdated or poorly enforced and institutional weakness creates unpredictability.
Together, these governance issues lead to a chronic shortage of “bankable” projects — projects that are well prepared, carry acceptable levels of risk and operate in countries where governance is stable enough to attract private investors. Banks and private investors consistently rate the forest sector as high risk, a perception that reflects real conditions rather than ignorance of the sector’s potential.
“The main lesson,” said study co-author Anja Gassner, “is that investors look for finance systems that are anchored in strong governance systems.”
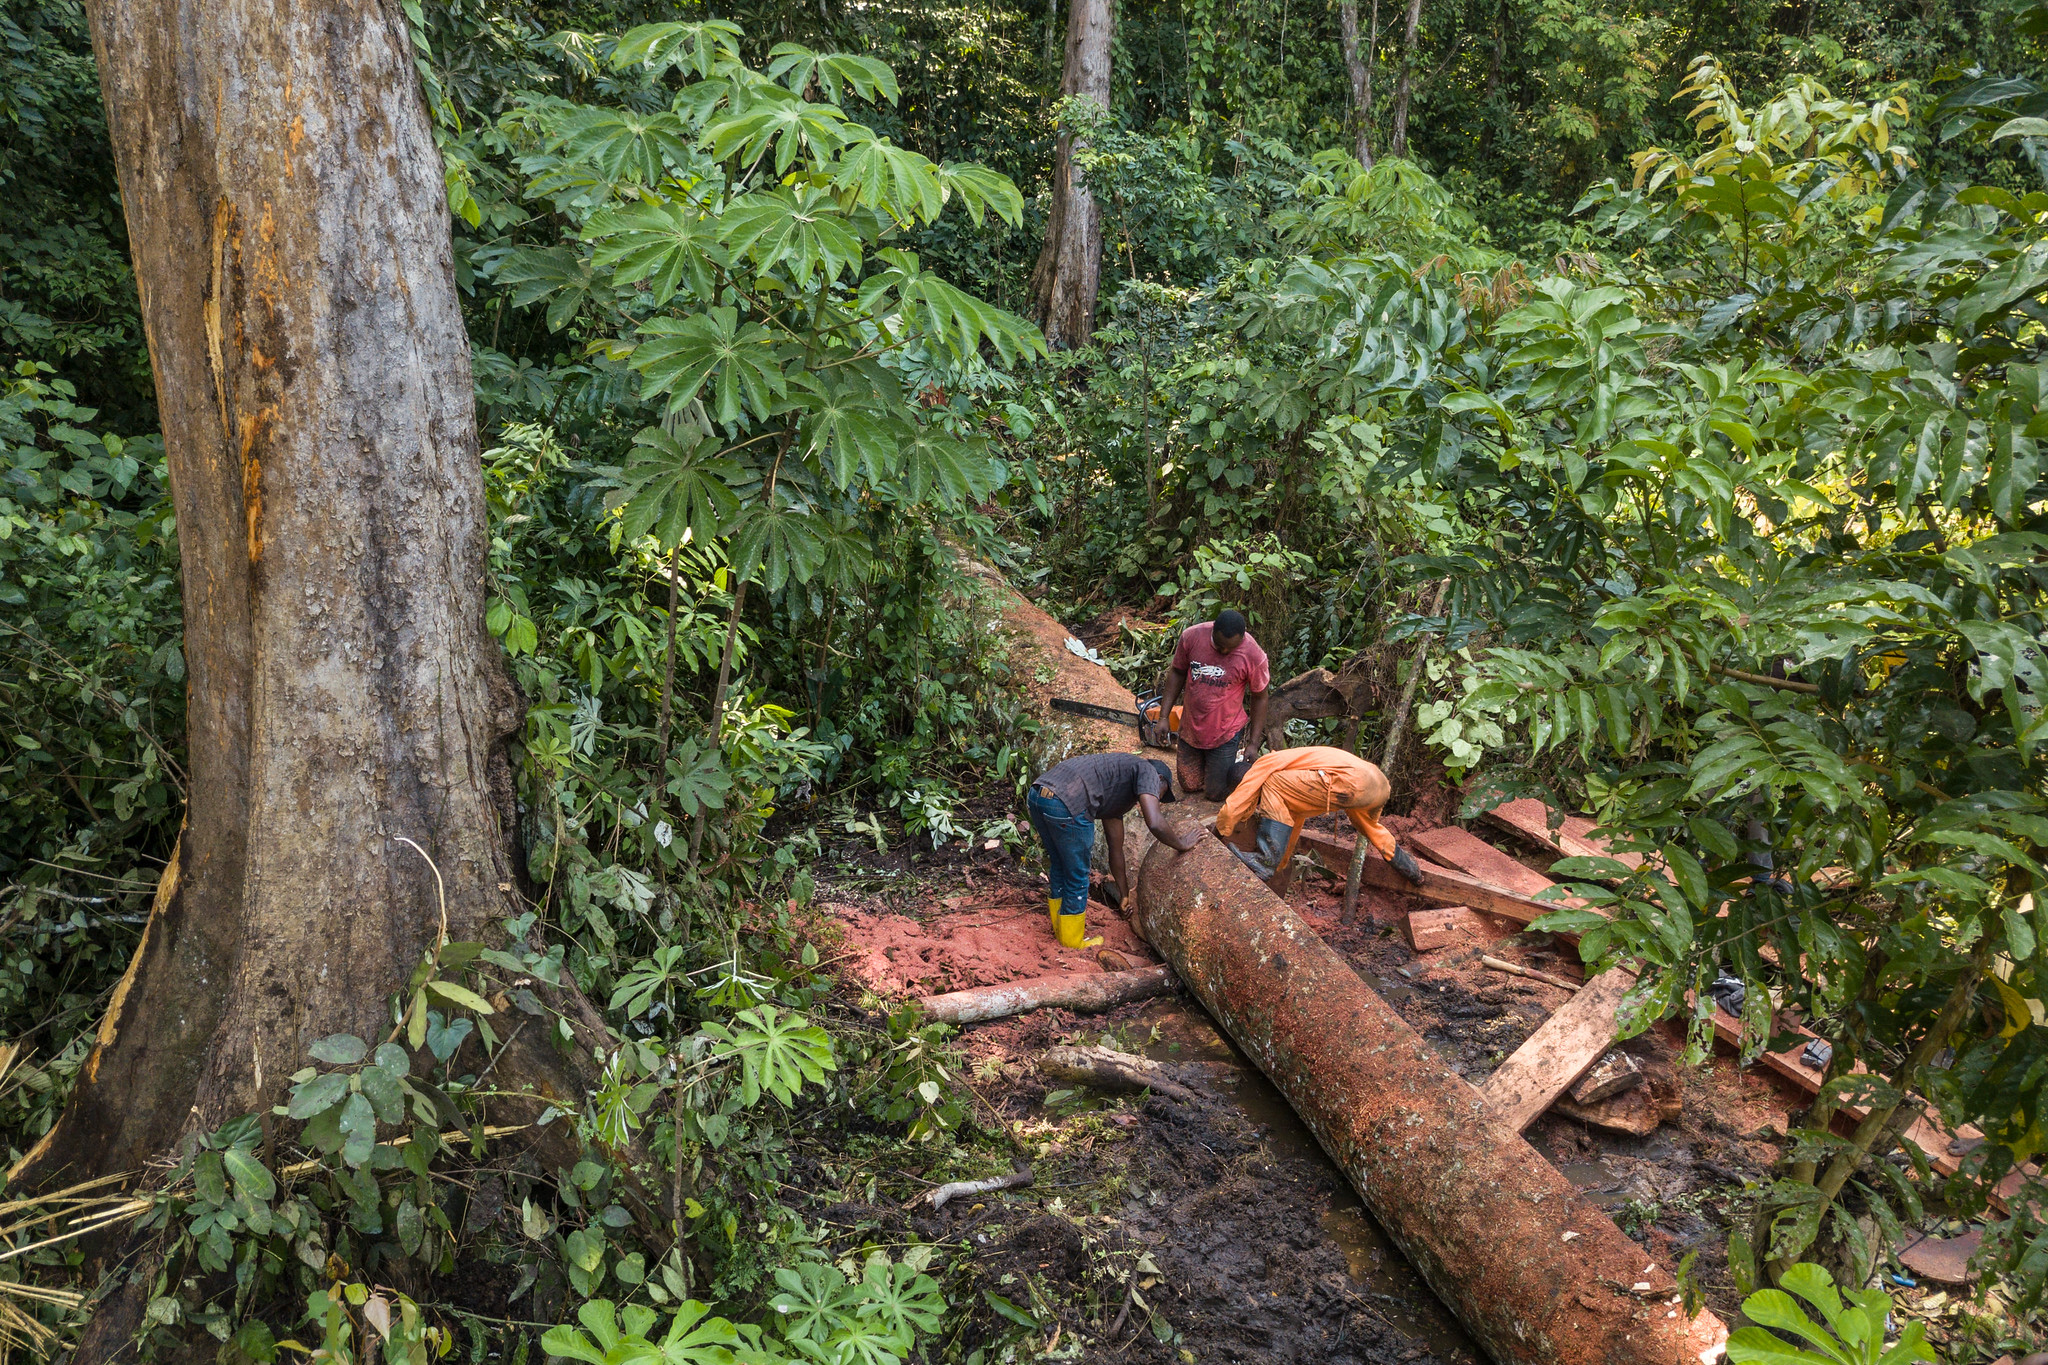
Finance initiatives still fragmented
The picture across the 11 countries is one of fragmentation. Most have accumulated pilot projects, national forest funds, conservation trust funds, payment for ecosystem services schemes, carbon finance programmes, and various forms of bilateral and multilateral donor support. But these mechanisms operate largely in silos, preventing the development of coherent, scalable systems.
This is especially true in the Congo Basin, where the foundation for many instruments exists and where the ecological stakes are among the highest on the planet. In these countries, because of significant fragmentation, strong individual components do not add up to an integrated approach. The result is a forest finance architecture that remains heavily donor-dependent and structurally unable to mobilize private capital at the scale required for restoration and sustainable management.
The report finds the clearest progress in more advanced instruments, particularly carbon markets anchored in REDD+ frameworks, national registries such as Guyana’s ART-TREES system and Colombia’s RENARE registry, and result-based payment mechanisms. Gabon, Guyana, Colombia, and Lao PDR have demonstrated that verified carbon transactions are achievable when institutional capacity and governance systems are in place.
Emerging instruments, including biodiversity credits, debt-for-nature swaps, green bonds, sustainability-linked bonds, and impact investment, show genuine potential in the countries where enabling frameworks exist. Gabon’s 2023 Blue Bond debt-for-nature swap and Colombia’s sovereign green bonds offer early examples of what becomes possible when governance is sufficient to attract sophisticated capital.
These are early cases, however. The conditions that made them possible are not yet replicable in most of the 11 countries assessed.
A CIFOR-ICRAF researcher collects data on forest carbon stocks. Photo by Nanang Sujana / CIFOR-ICRAF
Invest first in laying the groundwork
The report is especially relevant for initiatives aimed at promoting high-quality private investment. One finding deserves particular attention in the context of the European Union’s Global Gateway initiative, which positions private-sector investment as a central mechanism of international cooperation.
“The report’s analysis of forest-dependent communities involved in carbon finance and result-based payment projects draws an instructive analogy with microfinance,” said Robert Nasi, director general of CIFOR and director of science for CIFOR-ICRAF. “Deep inclusion of the most marginalized communities was achieved not through guarantees or risk transfer, but through patient, grant-like capital that strengthened institutional capacity and absorbed early losses.”
The implication is clear: grants must precede guarantees. The institutional conditions for private investment need to be built through sustained public and philanthropic support before private capital can function without shifting risk onto those least equipped to bear it.
“This is not a counsel against private finance,” Nasi added. “It is a precise description of the sequence required to make it work.”
The report’s core conclusion is that the problem is systemic. The solution is not another pilot project or another standalone instrument, but integrated forest finance systems in which public, private, and market-based mechanisms are coordinated rather than fragmented. Risk must be distributed appropriately across actors with the capacity to manage it, while fiscal policy, climate strategy, and biodiversity objectives need to be aligned rather than pursued separately.
Translating that conclusion into practice will be a multi-year undertaking in most of the countries assessed. It will require sustained investment in legal frameworks, institutional capacity, land tenure systems and governance reform.
“That investment is not yet being made at the required scale,” Nasi said. “The report provides a road map, but building the conditions under which those elements could actually function remains unfinished work.”
The report is part of the Forests for the Future Facility project.